Recently, digital supervision policies for the domestic logistics, ride-hailing, and construction machinery transport industries have continued to be implemented. Traffic management departments in many regions require freight and leased vehicles to be equipped with BeiDou positioning devices, and the vehicle GPS positioning terminal market is entering a period of rapid growth. According to industry research data, domestic vehicle positioning terminal shipments rose 42% year-on-year in the first half of 2026, with wired models supporting BeiDou+GPS dual-mode positioning and 9-90V wide voltage becoming the market mainstream.
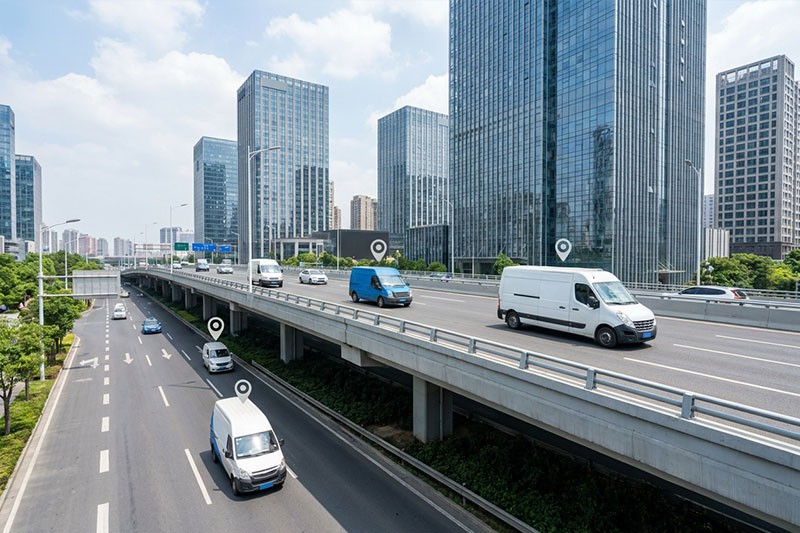
Traditional fleet management has long suffered from pain points such as missing vehicle trajectories, difficult overspeed control, unauthorized driving, and asset loss. The new generation of 4G full-network positioning terminals integrates four positioning modes - GPS, BeiDou, WIFI, and LBS - combined with electronic fences, ACC vehicle status detection, and real-time trajectory playback, perfectly meeting the mandatory supervision requirements of logistics fleets, school buses, and hazardous chemical transport vehicles. Taking the market hit GT06 positioner as an example, the device is compact at only 77mm28mm14.5mm, compatible with two-wire and four-wire wiring, covering all vehicle categories including electric vehicles, heavy trucks, and construction machinery, while supporting the JT/T808 national standard protocol and customized private protocols, and can seamlessly integrate with enterprises' own management platforms.
Overseas market demand is also heating up. Multiple countries in Southeast Asia, Europe, and South America have introduced vehicle traceability regulations, and orders for vehicle positioning devices with international frequency band versions have surged. Industry practitioners analyze that in the next two years, multi-function terminals with dual-mode BeiDou positioning, IP68 waterproofing, and expandable external sensor connections will gradually replace basic positioners. At the same time, OEM/ODM customization services have become the core competitiveness of manufacturers. Automakers, leasing groups, and logistics platforms are seeking deep cooperation with source hardware manufacturers to customize integrated vehicle monitoring software-hardware solutions.
Driven by policies and the digital transformation needs of enterprises, competition in the vehicle positioning track is gradually upgrading across hardware performance, platform support, and customization services. Source production enterprises with independent software-hardware R&D capabilities and multi-product-line layouts will continue to occupy a dominant market position, and intelligent vehicle location management will also become a standard configuration in the transportation industry.